Buying a home
Find the right home with a clearer path to buying it.
Guidance. Open search. A real person.
Buying is easier when you know what happens before, during and after the offer. Sapphire Realty helps buyers understand the process, evaluate properties and move forward without guessing — and the property search stays open: no account, no form, no email required to look.
Or call Alika direct: (909) 373-7214. No pressure and no obligation.
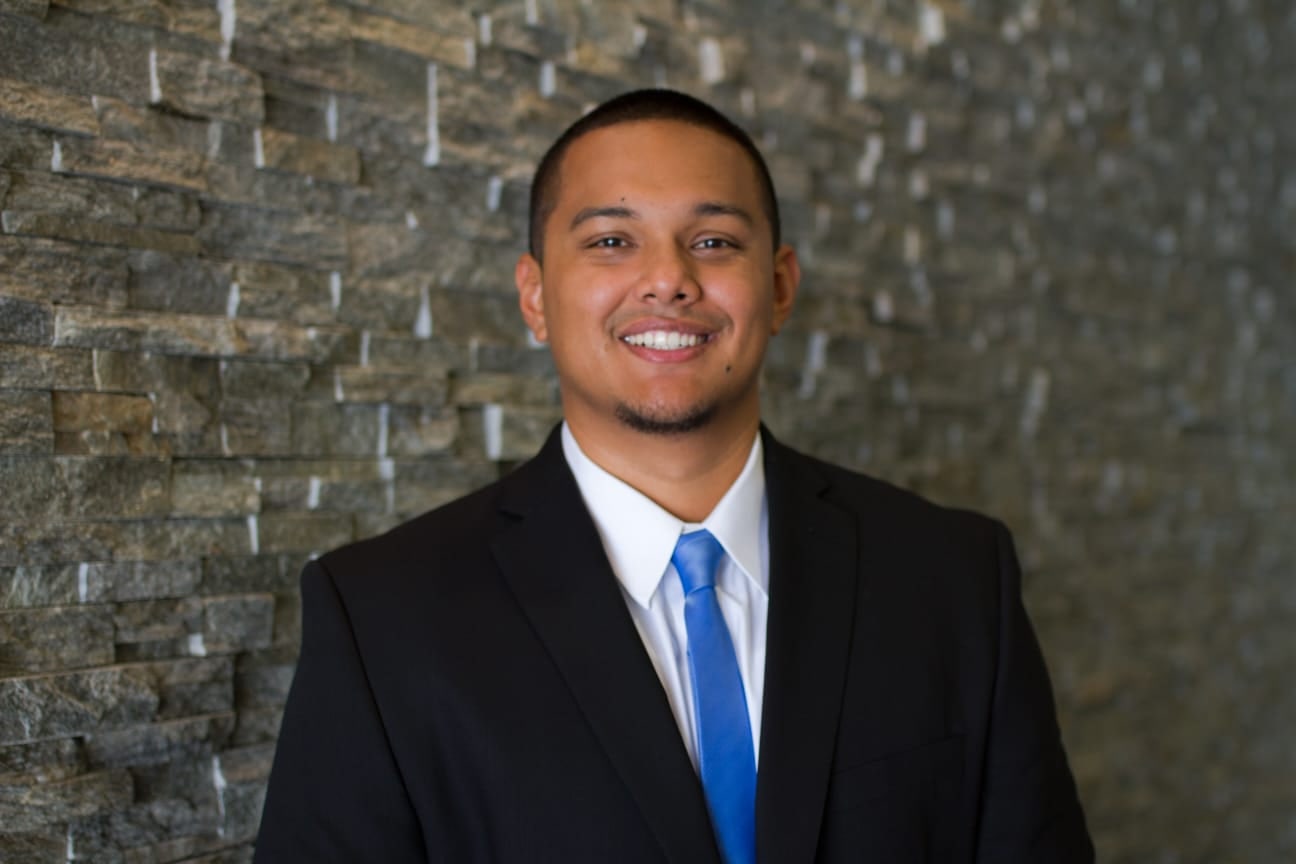 A real personAlejandro (Alika) Castellon Jr., Broker-Associate. The person you will actually talk to, from the first question to the closing table.
Nothing on this page needs a form to read. Asking is a request for information, not a commitment.
Where are you in the process?
Five stages, in the order they actually happen
Most of the stress in buying comes from not knowing what is next. Pick the line that sounds like you and the path opens at that stage — no form, no score, no judgement.
You are at stage 01 of 5 — Prepare
I’m getting ready
Talk with a lender about pre-approval and work out a practical search range based on the payment and your own budget — a pre-approval is a lender’s conditional statement, not a loan. Nothing on this page needs a form to read.
This is orientation, not advice. Nothing here scores you, qualifies you or rules anything out.
You are at stage 02 of 5 — Search
I’m starting my search
Search current listings available through CRMLS — no account needed to look — and read the area pages for the cities you are weighing. When a home raises a question, ask about it.
This is orientation, not advice. Nothing here scores you, qualifies you or rules anything out.
You are at stage 03 of 5 — Offer
I found a home I’m serious about
Ask about the property or request a showing — a request until Sapphire Realty confirms availability with you — then work out the terms, not only the price.
This is orientation, not advice. Nothing here scores you, qualifies you or rules anything out.
You are at stage 04 of 5 — Inspect and appraise
My offer was accepted
Schedule the inspection inside the contract window and answer your lender quickly if financing is involved — the lender may require an appraisal. Read the disclosures you receive.
This is orientation, not advice. Nothing here scores you, qualifies you or rules anything out.
You are at stage 05 of 5 — Close
I’m heading to closing
Watch for the Closing Disclosure where financing is involved, walk the home one last time, sign, and let funding and recording complete the purchase — possession follows the written agreement. Ask about any date you do not understand.
This is orientation, not advice. Nothing here scores you, qualifies you or rules anything out.
Stage 01 of 5
Prepare
What is happening
Understand your budget, how financing works and what a pre-approval tells you — and tells a seller. This is where a practical search range starts to take shape, before you fall for a house.
What you are deciding or doing
Settling what you can actually spend each month — not only the price — and whether to get a pre-approval before you shop. A pre-approval is a lender’s conditional statement, not a loan.
Where Alika helps
Explains what a pre-approval involves and why sellers care about it, and points you to a lender for the numbers. Sapphire Realty does not give lending advice.
What comes next
Searching with a practical range, so the homes you look at are homes you could realistically consider.
Stage 02 of 5
Search
What is happening
Compare homes, locations and trade-offs. Condition, commute, HOA rules and resale all matter; the search is where you learn what you actually value.
What you are deciding or doing
Choosing the areas you would consider, the must-haves and the trade-offs you can live with — and using the live property search, which needs no account to look.
Where Alika helps
Reads a listing with you — what the remarks, the price and the condition really mean — compares homes and neighborhoods with you, and can help arrange a showing. Sapphire Realty confirms availability with you.
What comes next
A home you are serious enough about to write on.
Stage 03 of 5
Offer
What is happening
Price is one term among several. Contingencies, timing, deposit and what stays with the home all shape whether an offer works — and how it is received.
What you are deciding or doing
Deciding the price, the contingencies you keep, the deposit and the timing — then whether to accept, counter or walk away when the seller responds. Nothing binds until both sides sign the same terms.
Where Alika helps
Prepares an offer with price, terms and contingencies that fit your situation, and explains what a counter means before you answer it.
What comes next
Acceptance — the transaction moves into escrow on the written terms.
Stage 04 of 5
Inspect and appraise
What is happening
After acceptance, the inspection tells you about the home. Where financing is involved, the lender may require an appraisal, which tells the lender about the price. Either can change the deal, and both are normal.
What you are deciding or doing
Scheduling the inspection within the window your contract allows, deciding how to respond to what it finds, and reading whatever disclosures you receive carefully.
Where Alika helps
Explains what the inspection can and cannot tell you, what a low appraisal means if one is required, and what happens if either raises a concern.
What comes next
Contingencies are handled according to the written contract; deadlines and any required written removals matter as the file moves toward closing.
Stage 05 of 5
Close
What is happening
Escrow, final walkthrough, signing and funding. Funding and recording complete the purchase; possession follows the written agreement. We explain what each date on the calendar means and what is expected of you.
What you are deciding or doing
Reviewing the closing documents — where financing is involved, comparing the Closing Disclosure with your Loan Estimate — the final walkthrough, then signing. Timing depends on the lender, the property and escrow.
Where Alika helps
Coordinates through closing — lender, escrow, inspections and the final walkthrough — and explains what each date on the calendar means and what is expected of you.
What comes next
Funding and recording complete the purchase; possession follows the written agreement.
Timelines depend on the lender, the property and escrow. Nothing here is a promised date, and nothing here is legal, tax or lending advice. The four written guides go deeper on stages 01, 03, 04 and 05.
Before you write an offer
Six things worth understanding first
None of these should stop you. They are the questions we would want answered before committing to a home — and the ones we help you work through.
Factor 1 of 6
Monthly payment vs purchase price
The purchase price is one number; the monthly payment is the one you live with. Interest, taxes, insurance and any HOA dues all shape it.
A lender can show you the full picture for a specific home. Sapphire Realty does not quote rates or give lending advice.
Factor 2 of 6
Property condition
Photos show the best angle. Age of the roof, systems, drainage and past repairs affect what you will spend after closing. Condition is a reason to look closer, not necessarily a reason to walk away.
An inspection, once you are under contract; before that, ask Alika what the listing leaves out.
Factor 3 of 6
Neighborhood and location fit
Commute, noise, parking and how the street feels at different times of day. A home that fits on paper still has to fit your week.
You — it is your week. Alika can compare the trade-offs between homes and locations with you; Sapphire Realty does not rank neighborhoods.
Factor 4 of 6
Disclosures
California residential transactions can involve required seller disclosures, depending on the property and the transaction. Reading whatever you receive carefully — and asking about anything unclear — is part of deciding, not a formality to sign through.
Read them; ask Alika about anything unclear. Questions about your legal position belong with a California attorney.
Factor 5 of 6
Inspection and appraisal
An inspection is your chance to learn what you are buying. Where financing is involved, the lender may require an appraisal — the lender confirming the price. Understand what each can and cannot tell you, and what happens if either raises a concern.
The inspector for the home; the lender for whether an appraisal applies and what it means for the loan.
Factor 6 of 6
Offer terms and contingencies
Contingencies protect you while questions get answered; removing them changes your risk. The right terms depend on the home, the market and your situation — not on a script.
Alika, for terms that fit your situation. Nothing binds until both sides sign the same terms.
Location fit is about your own week — commute, noise, parking, how a street feels. Sapphire Realty does not rank neighborhoods and does not publish school, safety or demographic claims.
Ready to see what is available?
Search current listings, then ask about any home.
Search current listings through CRMLS, then ask Alika about any home you want to understand better. You do not need an account to look, and nothing on this site claims exclusive inventory — the search shows current listings available through CRMLS.
- See current listings — homes on the market through CRMLS, updated by the MLS.
- Use the map and filters — price, beds, baths, property type and location.
- Save what catches your eye — a free CRMLS account keeps favourites and saved searches; it is optional.
- Ask about any home — send the address and Alika explains what the listing actually means.
Live property search powered by CRMLS. Results, prices and statuses come from the MLS — not from this page.
Go deeper
Four written guides, keyed to the stages
General education, not legal, tax or lending advice. The full library is on Learn; the area pages are on Areas.
The questions buyers ask most
Short answers, each also a page of its own
Should I get pre-approved before I start seriously shopping for a home?
In most cases, yes — it is one of the most useful early steps. A pre-approval is a lender’s conditional statement of how much it may be willing to lend you, based on information you provide and, usually, documents it verifies. It tells you the price range that is realistic for your budget, shows sellers that a lender has already looked at your finances, and lets you move quickly when the right home appears.
It is not a guarantee of a loan. The final approval still depends on the property, the appraisal and a full underwriting review, and letters typically carry an expiration date.
Browsing before you are pre-approved is fine — the property search on this site is open to everyone — but before you write an offer, most sellers and their agents will want to see a letter. The Financing & Pre-Approval guide explains what lenders look at and how to compare Loan Estimates.
What is the difference between pre-qualification and pre-approval?
Lenders do not use these two words consistently, so the label matters less than what the lender actually did. In general, a pre-qualification is an informal estimate based on information you describe — income, debts, savings — without documents being checked. A pre-approval usually means the lender has reviewed some verification, such as pay stubs, bank statements and a credit report, and has written a letter stating the amount it may lend on certain assumptions.
The Consumer Financial Protection Bureau’s advice is to ask the lender what it verified rather than relying on the word printed on the letter. Neither one is a loan commitment: both are conditional, both can expire, and the final decision waits for a specific property and full underwriting.
When you are ready to make offers, the more thoroughly verified letter carries more weight with sellers. More in the Financing & Pre-Approval guide.
How much money do I need beyond the down payment?
Plan for several costs on top of the down payment. Closing costs are usually the largest: lender charges, appraisal and credit-report fees, title and escrow services, prepaid property taxes and homeowners insurance, and interest up to your first payment. Consumer guidance from Freddie Mac describes closing costs as commonly a few percent of the purchase price, but the real figure depends on the loan, the property and what is negotiated — your lender’s Loan Estimate lists them for your specific loan.
Expect an earnest money deposit when your offer is accepted — a good-faith deposit that is normally credited toward your purchase at closing. Budget for a home inspection, which you pay for directly, and for moving, utility set-up and any immediate repairs. Depending on the loan program, the lender may also want to see savings left over after closing.
Ask your lender early for a written estimate so nothing surprises you on the day. The Closing guide lists what to bring and what to check.
What is the difference between a home inspection and an appraisal?
They happen around the same time but answer different questions for different people.
A home inspection is for you. You choose and pay a professional home inspector to examine the property’s condition — roof, structure, plumbing, electrical, heating and cooling and more — and report what is worn, damaged or worth a closer look by a specialist. It does not put a value on the home.
An appraisal is for the lender. The lender orders it, you typically pay for it, and a licensed appraiser gives a written opinion of what the property is worth so the lender knows the home supports the loan amount. You are entitled to a copy.
An appraisal is not a condition report, and an inspection is not a valuation. Many buyers make their offer contingent on both, which keeps options open if the inspection reveals serious issues or the appraisal comes in below the agreed price. The Inspection vs Appraisal guide goes deeper.
What happens after my offer is accepted?
Acceptance starts the period between contract and closing — in California this stretch is commonly called “being in escrow.” Your earnest money deposit is placed with the escrow holder. Your lender begins full underwriting and will ask for documents; answering quickly keeps the timeline on track.
You schedule the home inspection within the window your contract allows and decide how to respond to what it finds. The lender orders the appraisal. You shop for homeowners insurance and review the title work. The seller delivers the written disclosures California requires for most residential sales, and you read them. Watch for revised Loan Estimates if anything about the loan changes.
At least three business days before closing you receive the Closing Disclosure, which you should compare with your Loan Estimate. Then a final walk-through, signing, funding and recording. The Closing guide walks through each step, including how to protect yourself from wire-fraud scams.
Can I request a showing for a home I find in the property search?
Yes. The property search on this site shows current listings available through CRMLS, the regional multiple listing service. When a home interests you, note its address or MLS number and send a property inquiry or showing request through the contact page, or call Alika directly at (909) 373-7214.
A showing request is exactly that — a request. It is not a confirmed appointment until Sapphire Realty confirms availability with you. We check the property’s showing instructions and the seller’s availability, then contact you to agree a time; some homes have limited access, tenants in place or specific showing windows. Nothing is booked automatically.
Requesting a showing does not commit you to anything, and you do not need to be pre-approved or already working with an agent to ask a question about a home.
Not sure where to start?
Look at what is available, or describe what you are after.
You do not need to have everything figured out before asking a question. Search, or tell a person roughly what you are looking for — either is a fine first step.
Alika direct (909) 373-7214 · Office (909) 244-9047 · Se habla español. No pressure and no obligation.